

Running a business that falls into a high-risk category can make accepting credit cards more challenging, even when the company operates legitimately and serves customers responsibly. Secure credit card processing high-risk businesses require starting with understanding how payment providers evaluate transactions, chargebacks, fraud exposure, and monthly processing volume.
A high-risk classification does not automatically mean a business is unreliable. Industries such as e-commerce, travel, credit repair, and certain subscription services may face additional scrutiny because of their transaction patterns or potential disputes.
Choosing a suitable payment provider means looking beyond initial approval. Businesses should examine fraud prevention, PCI compliance, settlement arrangements, contract conditions, and customer payment options before making a commitment.
Why Merchant Services High Risk Businesses Need Matter
Reliable merchant services high risk businesses can access are important when traditional payment providers decline applications or impose restrictive conditions. A dedicated high-risk account can help eligible merchants accept card payments while addressing the particular challenges associated with their industries.
Chargebacks, suspected fraudulent transactions, unusually high average transaction values, and card-not-present payments can all influence underwriting decisions. Understanding these factors helps business owners prepare stronger applications and identify areas where operational improvements may reduce payment risks.
Payment acceptance should also fit the way a company actually operates. Businesses processing online orders may need different fraud controls from service providers accepting payments through virtual terminals. Reviewing transaction methods, anticipated volume, and customer purchasing patterns can help merchants find a more appropriate solution.
Evaluating the Merchant Services for Professional Services Firms
Finding the best merchant services for professional services firms requires attention to more than transaction rates. Consultants, agencies, specialized service providers, and other professional businesses should assess whether a provider understands their billing structure, recurring payments, average transaction sizes, and potential dispute risks.
Professional services firms may receive payments for consultations, project milestones, retainers, or ongoing service agreements. Clear invoices, written service terms, and accessible customer support can help reduce misunderstandings that sometimes lead to chargebacks.
When comparing providers, request a complete explanation of processing charges, account fees, reserve requirements, and cancellation conditions. The best merchant services for professional services should support the company’s payment workflow while providing clear contractual terms and practical risk-management options.
Comparing Top Merchant Services Companies Beyond Advertised Rates
Comparing top merchant services companies requires a closer look at the actual agreement rather than relying on promotional claims. An attractive advertised rate may not reveal additional transaction charges, monthly minimums, compliance costs, reserve requirements, or early termination penalties.
For high-risk merchants, processing expenses can be substantially higher than traditional account costs. The reviewed guide notes that some high-risk accounts may cost three to ten times as much, depending on the business’s risk assessment. This is a general industry comparison, not a quote for an individual merchant.
Ask each provider to explain its pricing structure in writing and distinguish debit card rates from credit card rates. Comparing total costs against your actual transaction volume provides a more useful picture than choosing a provider based solely on its advertised starting rate.
Building Credit Card Processing High-Risk Businesses Can Trust
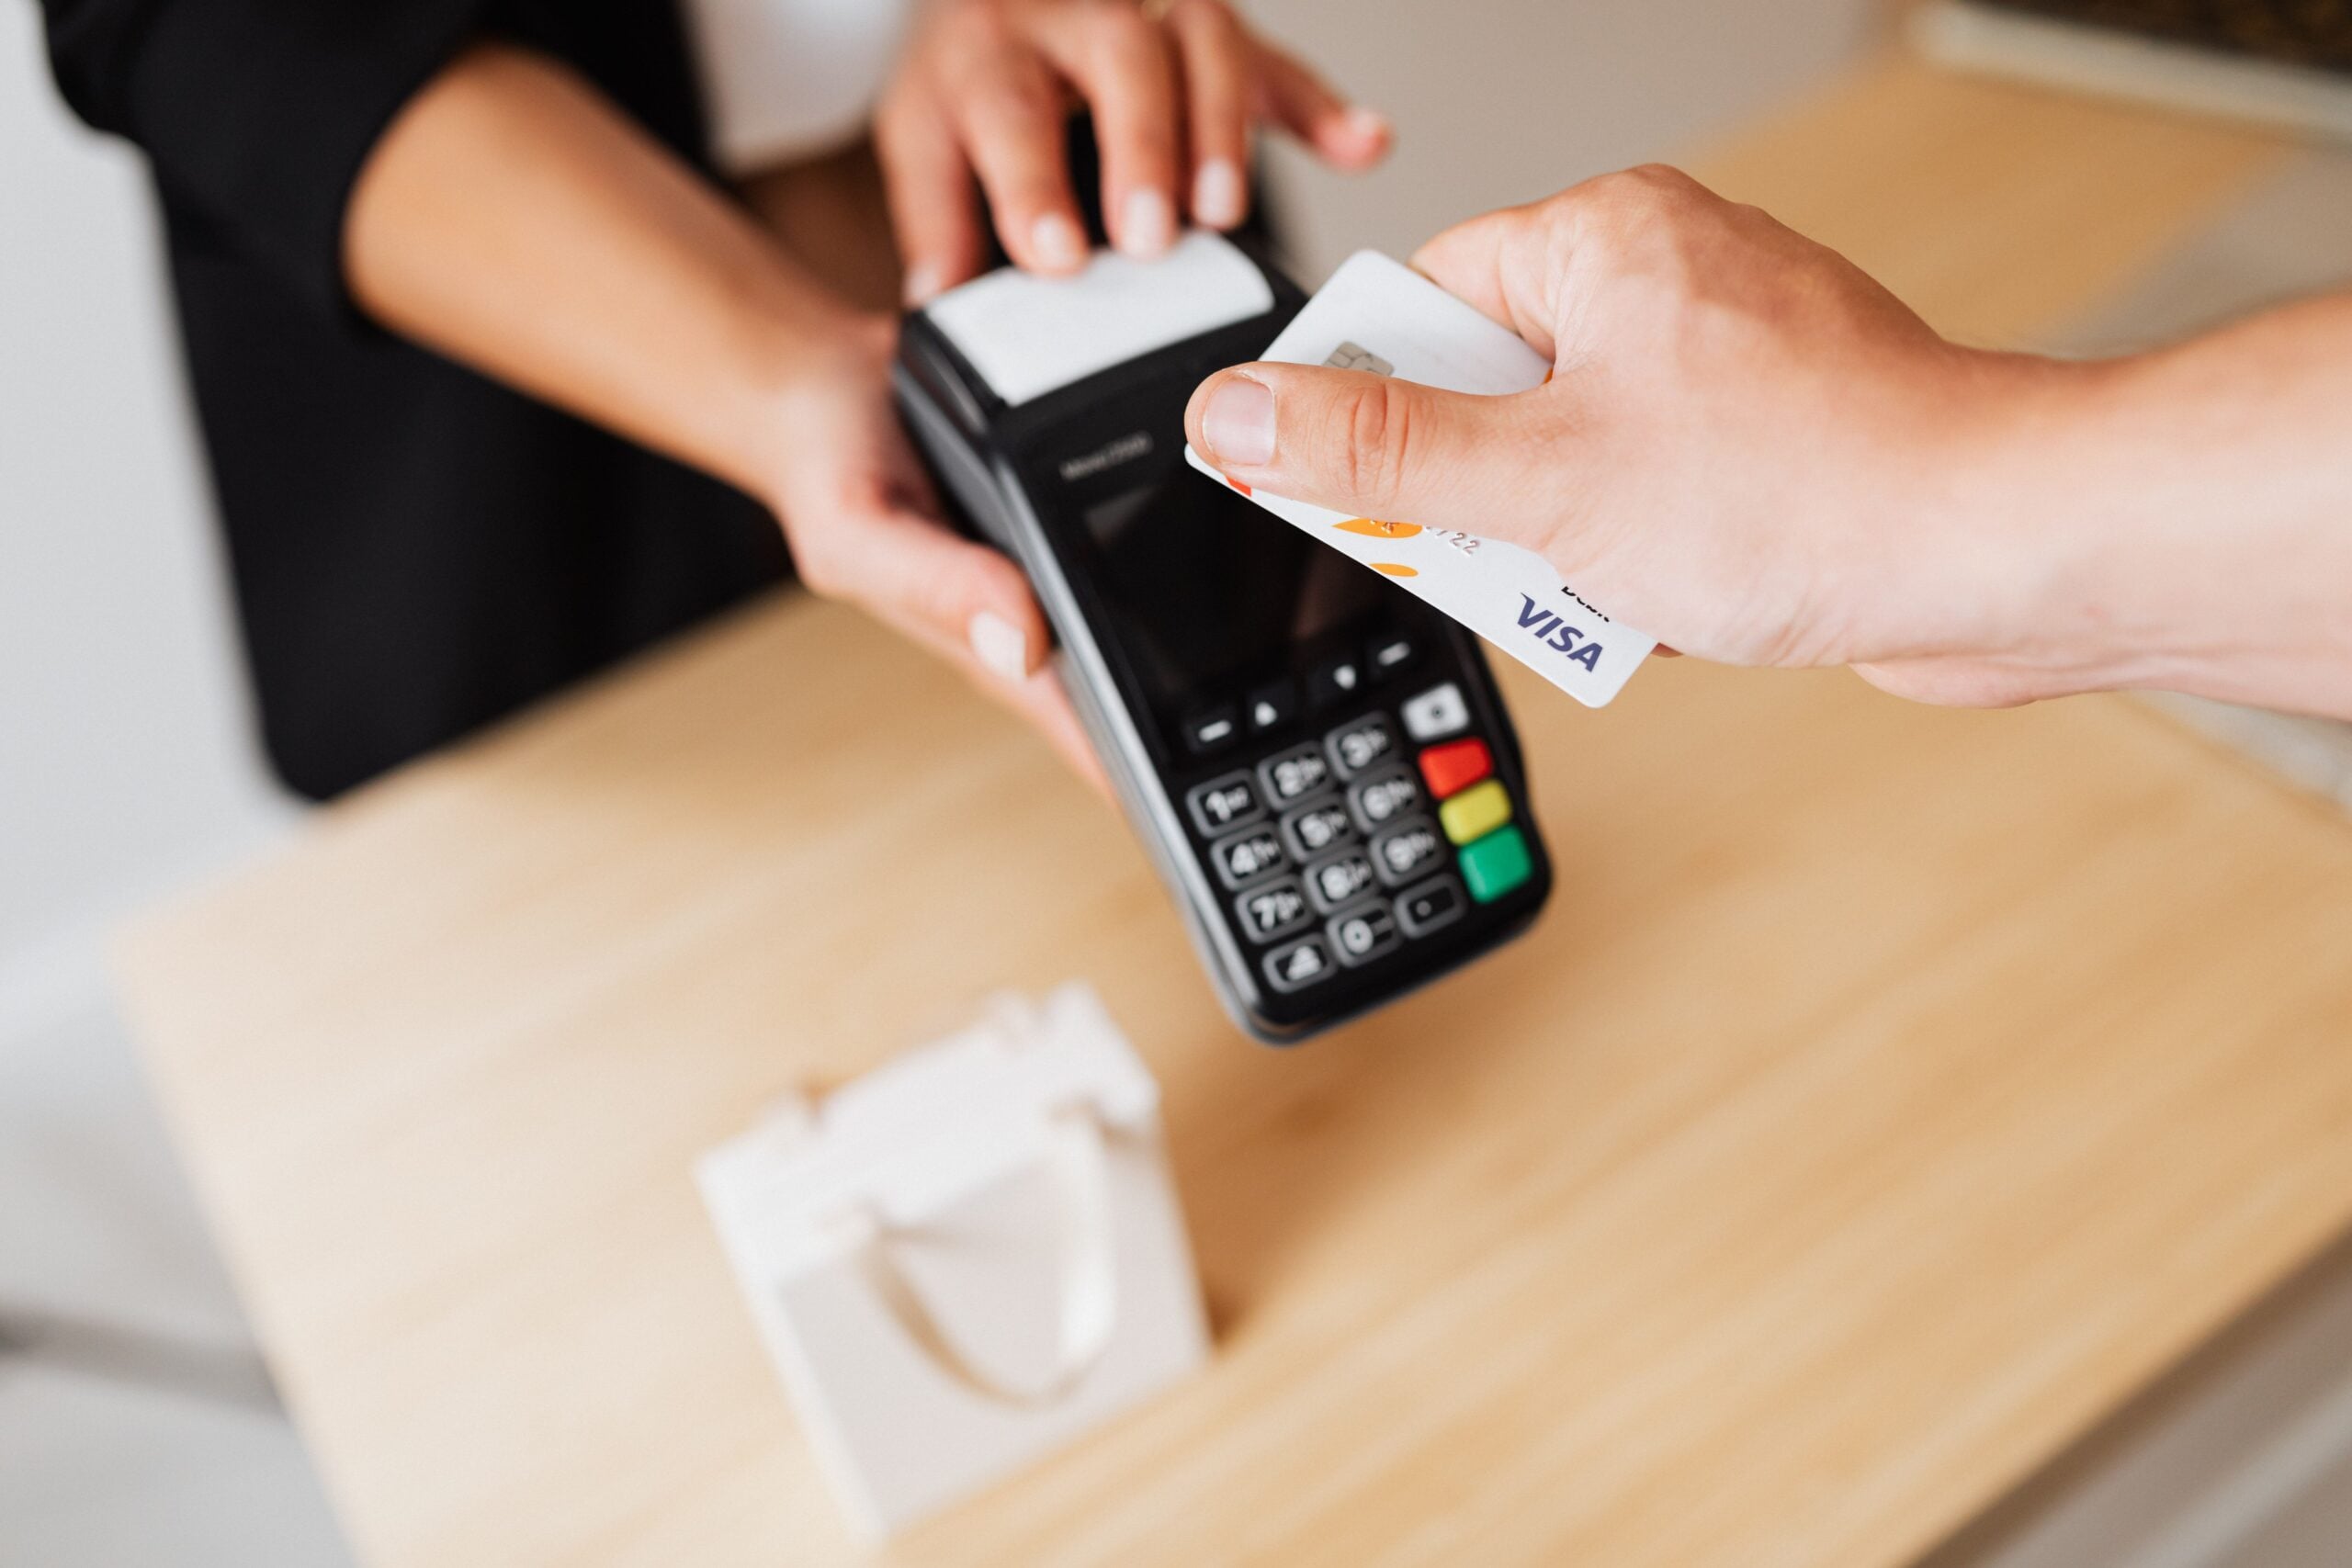
Secure credit card processing on high risk businesses can depend on involves several layers of protection, including fraud screening, PCI compliance, transaction monitoring, and appropriate dispute-handling procedures. These measures help merchants manage payment exposure while maintaining a smoother checkout experience for legitimate customers.
Payment providers may use fraud-screening tools to identify suspicious activity before it creates additional losses. Businesses can strengthen those efforts by reviewing unusual orders, maintaining accurate transaction records, communicating refund policies clearly, and responding promptly to customer concerns.
No payment system can eliminate every fraudulent transaction or chargeback. However, selecting a provider that understands high-risk processing and offers relevant security measures can help businesses establish more consistent payment operations without treating every transaction as equally risky.
Understanding Contract Terms, Reserves, and Hidden Fees
Merchant agreements deserve careful attention because contractual conditions can affect cash flow long after an account receives approval. High-risk merchants should examine monthly charges, transaction fees, rolling reserves, settlement conditions, minimum processing commitments, and any penalties associated with ending an agreement.
A rolling reserve means a processor temporarily withholds a portion of transaction proceeds to help cover potential chargebacks or other liabilities. The amount, release schedule, and applicable conditions should be explained before signing, because withheld funds may influence working capital and everyday operating expenses.
Where available, month-to-month arrangements can offer more flexibility than lengthy commitments. Review every clause carefully, ask for clarification on unfamiliar terminology, and obtain written answers about fees. Transparent merchant services high risk businesses can use should make financial obligations understandable before processing begins.
Improving Approval Readiness and Reducing Chargebacks
Preparing a strong application can improve the process of finding a suitable payment provider. Businesses should organize their business registration details, website information, refund policies, transaction estimates, and relevant processing history before applying for a merchant account.
Providers may assess previous chargebacks, fraud patterns, average ticket size, business credit, and the nature of the products or services being sold. Secure credit card processing high-risk businesses seek is easier to evaluate when applicants provide accurate information and explain how they handle disputes and customer complaints.
After approval, merchants should monitor chargeback trends and investigate recurring problems instead of treating every dispute as an isolated event. Clear billing descriptors, prompt customer service, documented transactions, and transparent cancellation terms can help reduce avoidable disputes and support healthier payment operations.
Exploring Flexible Payment Options for High-Risk Merchants
Payment flexibility can be valuable for merchants who want to manage processing expenses while accommodating different customer preferences. Depending on eligibility and applicable rules, providers may offer conventional processing, zero-fee processing arrangements, or cash discount programs.
A cash discount program is different from simply adding an undisclosed charge at checkout. The program must be structured and communicated appropriately, with applicable card-network rules and local laws considered before implementation. Merchants should ask providers to explain the precise arrangement, customer disclosures, and any associated costs.
When evaluating the best merchant services for professional services firms, consider whether available payment options suit your billing practices and customer expectations. Comparing top merchant services companies on flexibility, compliance guidance, contract clarity, and support can help businesses identify arrangements that make sense for their operations.
Choosing a Payment Partner for Sustainable Business Growth
Selecting secure credit card processing high-risk businesses need is ultimately about finding a provider that understands the company’s specific circumstances. Approval figures, processing speed, security measures, and advertised savings can be useful considerations, but each claim should be examined alongside the actual agreement and eligibility requirements.
Before committing, compare merchant services, high risk providers on total costs, reserve policies, cancellation conditions, fraud prevention, and customer support. Professional service providers should also consider whether the proposed account accommodates their invoicing practices, recurring transactions, and typical payment amounts.
The best merchant services for professionals and other specialized businesses are those that balance practical payment acceptance with transparent financial terms. By comparing top merchant services companies carefully, asking informed questions, and prioritizing secure credit card processing high-risk requirements, merchants can make more confident decisions and build a stronger foundation for long-term growth.