Financial Technology Company for Sale
The financial technology industry has changed how individuals and businesses manage money, access financial services, and conduct transactions. Digital payment systems, online lending services, investment applications, and financial management software have become important parts of the modern economy. As demand for convenient financial solutions continues to influence the market, acquiring an established fintech business can be an opportunity for entrepreneurs and investors seeking an entry into this sector.
Searching for a financial technology company for sale involves more than finding a business with an attractive price. Buyers need to understand its technology, revenue sources, customer relationships, regulatory responsibilities, and potential for sustainable growth. A company may have an impressive product but still face challenges related to customer retention, operating costs, cybersecurity, or competition.
A structured acquisition process helps prospective buyers evaluate these factors before making a commitment. By examining the business model, reviewing financial information, and assessing future opportunities, investors can make more informed decisions about whether a fintech acquisition matches their objectives.
What Is a Financial Technology Company?
A financial technology company, commonly called a fintech business, uses software, digital infrastructure, or data-driven systems to provide or improve financial services. These businesses may serve individual consumers, small companies, financial institutions, or large corporate clients.
Some fintech companies focus on simplifying everyday transactions, while others develop specialist tools for accounting, lending, wealth management, or financial compliance. Their operations can range from consumer-facing mobile applications to complex software platforms used by professional financial organisations.
Unlike a traditional financial institution that may depend heavily on physical branches, a technology-focused financial business can deliver many services through websites, mobile applications, and integrated digital systems. However, the exact operating model depends on the company’s products and the jurisdictions in which it operates.
For buyers, understanding this distinction is essential. Acquiring a software provider that supplies tools to banks can involve different risks from purchasing a business that directly holds customer funds or issues loans.
Why Investors Consider Buying an Established Fintech Business
Building a fintech company from the beginning requires time, technical expertise, product development, and customer acquisition investment. Purchasing an existing business may provide access to an established product, experienced employees, existing customers, and operational systems.
An acquisition can also help a buyer enter a specialised market more quickly. For example, an investor interested in financial reporting software may consider purchasing a company with a developed product and an existing customer base rather than building an entirely new solution.
Established businesses may also have commercial relationships that would take considerable effort to develop independently. These relationships could include partnerships with payment processors, software vendors, banks, or business customers.
Nevertheless, an existing company is not automatically a safer investment. Its technology may require expensive updates, customers may be dissatisfied, or important commercial agreements may be difficult to transfer. Buyers should evaluate the actual condition of the business rather than relying on its age or reputation.
Catagories of Financial Technology Companies
The fintech sector includes several business categories, each with different commercial characteristics.
Digital Payment Businesses
Payment technology companies develop systems that help merchants and consumers complete electronic transactions. Their products may include payment gateways, billing tools, transaction-processing software, or merchant management systems.
When evaluating a payment business, buyers should examine transaction volumes, customer concentration, processing costs, fraud exposure, and the company’s relationships with payment partners. They should also establish whether required licences, registrations, and contractual arrangements can remain valid after the acquisition.
Financial Software Providers
Financial software companies supply tools for accounting, budgeting, reporting, reconciliation, and financial administration. Their customers may include small businesses, accountants, corporate finance departments, and professional service providers.
A business with reliable subscription revenue and strong customer retention may be attractive to buyers seeking recurring income. However, software maintenance, product compatibility, technical support, and competition can influence future performance.
Online Lending Platforms
Some fintech companies connect borrowers with lenders or provide technology for loan applications, underwriting, and repayment administration. Others operate lending businesses directly, subject to applicable legal requirements.
These businesses require careful examination of credit risk, funding arrangements, customer complaints, loan performance, and regulatory obligations. Buyers should clearly understand whether the company acts as a technology intermediary, a lender, or a combination of both.
Wealth Management and Investment Technology
This category includes digital investment tools, portfolio management software, financial planning applications, and platforms that support investment professionals.
Potential buyers should review the company’s fee structure, customer retention, data security, product functionality, and any permissions required for its activities. Where the business provides regulated investment services, compliance responsibilities deserve particular attention.
Banking Technology and Financial Infrastructure
Some fintech businesses develop application programming interfaces, identity verification systems, payment infrastructure, or software that financial institutions integrate into their own services.
These companies may benefit from long-term business relationships, but their commercial performance can depend on a relatively small number of major customers. Buyers should assess contract duration, service commitments, system reliability, and the cost of maintaining integrations.
Where to Find a Financial Technology Company for Sale
Finding a suitable acquisition target begins with identifying businesses that match the buyer’s financial resources, technical knowledge, and commercial goals.
Business-for-sale marketplaces may advertise technology companies seeking new ownership. Mergers and acquisitions advisers can help buyers identify opportunities that are not publicly advertised. Industry networks, specialist investment firms, and professional contacts may also provide introductions to potential sellers.
Direct outreach is another possible approach. Buyers can identify companies operating in a specific fintech niche and contact their owners to explore whether a sale or strategic partnership might be considered.
Before contacting sellers, it is useful to define a clear acquisition profile. This should include the preferred business category, approximate investment range, target markets, revenue model, and the level of operational involvement the buyer is prepared to undertake.
A focused search is generally more productive than reviewing every available technology business. It allows buyers to concentrate on companies whose products, customers, and operational requirements fit their plans.
How to Evaluate a Financial Technology Company for Sale
A detailed evaluation helps establish whether a potential acquisition is commercially viable and operationally sustainable.
Review Financial Performance
Buyers should examine historical financial statements, revenue trends, operating expenses, cash flow, outstanding liabilities, and working capital requirements. It is important to understand how the company generates income and whether that income is repeatable.
Subscription revenue, transaction fees, licensing income, and service contracts may each behave differently during periods of market change. Buyers should identify the proportion of revenue that depends on individual customers, short-term agreements, or unusual one-time transactions.
Financial information should be supported by appropriate records rather than accepted solely on the basis of seller-provided summaries.
Assess the Technology
The company’s software is often central to its value. Buyers should review the quality of its codebase, system architecture, hosting arrangements, development practices, documentation, and maintenance history.
They should also identify outdated components, unresolved technical problems, integration limitations, and planned upgrades. An independent technical assessment can help estimate the cost of maintaining or improving the platform after the purchase.
Intellectual property ownership must also be verified. The buyer should establish whether the company owns its software or depends on third-party licences, contractors, or technologies that impose restrictions.
Examine the Customer Base
Customer relationships can contribute significantly to the stability of a fintech business. Buyers should evaluate retention rates, customer acquisition costs, satisfaction levels, support requirements, and the reasons customers leave.
A company that depends heavily on a single client may face greater commercial risk than one serving a broader customer base. Similarly, rapid customer growth may not be sustainable if acquisition costs exceed the long-term revenue generated by those customers.
Reviewing customer contracts and service obligations can reveal whether important relationships are likely to continue following a change in ownership.
Investigate Security and Compliance
Financial technology companies may handle confidential information, transaction records, identity documents, or other sensitive data. Security weaknesses can create financial, legal, and reputational consequences.
Buyers should examine cybersecurity controls, access permissions, incident history, backup procedures, data retention practices, and disaster recovery arrangements. They should also assess privacy obligations and the company’s approach to preventing fraud.
Regulatory requirements depend on the products offered and the jurisdictions involved. Specialist legal and compliance advisers should identify the relevant obligations before the acquisition is completed.
Understanding the Valuation of a Fintech Business
The value of a financial technology company depends on several factors, including financial performance, growth prospects, technology quality, market position, and risk exposure.
Businesses with predictable recurring revenue, strong customer retention, and efficient operations may attract interest from buyers looking for established income streams. Companies with promising technology but limited commercial traction may require a different valuation approach.
Common valuation methods include analysing comparable transactions, applying suitable earnings-based measures, and estimating future cash flows. The appropriate method depends on the company’s business model, maturity, profitability, and available financial information.
Buyers should avoid relying on a single headline valuation or an unsupported growth forecast. Instead, they should compare reasonable scenarios, test the assumptions behind projected earnings, and estimate how much additional investment may be needed after closing.
The final purchase price should reflect both the business’s demonstrated performance and the risks that the buyer will assume.
Common Risks in Fintech Acquisitions
Technology acquisitions can involve risks that are not immediately visible in a sales listing. A platform may depend on a small development team, an expiring software licence, or a third-party provider that can change its pricing or service terms.
Other risks include cybersecurity incidents, regulatory changes, customer concentration, inaccurate financial reporting, and weak internal controls. A company may also face challenges if its product has not kept pace with changing customer expectations.
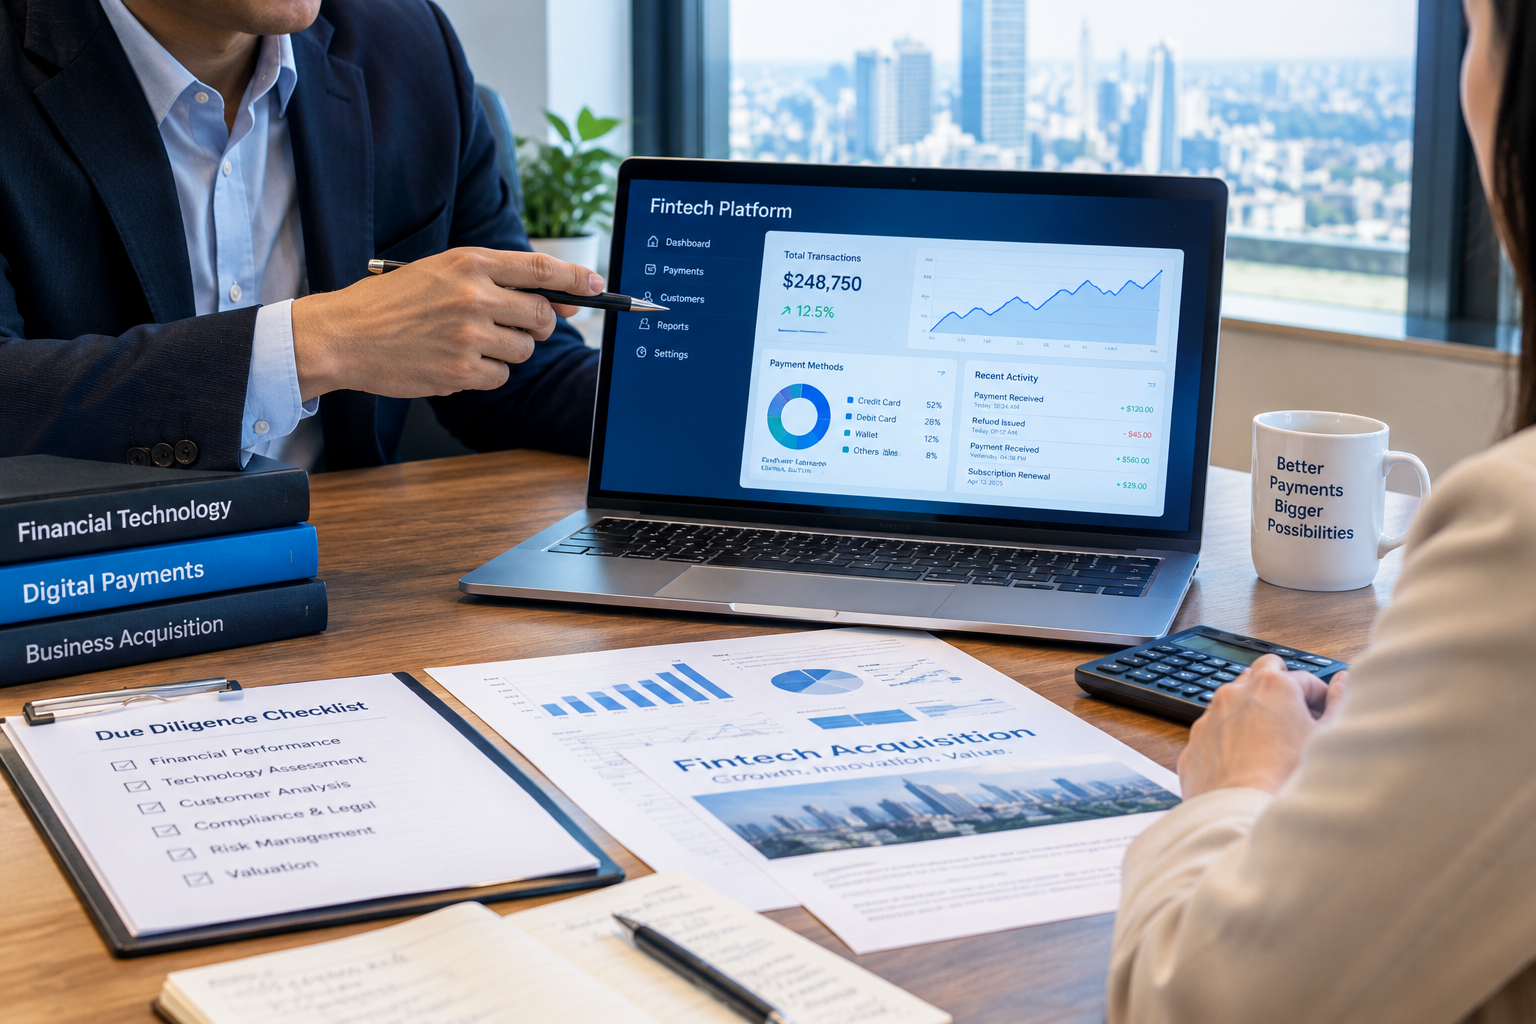
Buyers can reduce uncertainty through comprehensive due diligence. This process may include financial reviews, legal investigations, technical audits, customer-contract assessments, and compliance evaluations.
Any significant issue should be reflected in the acquisition terms, the valuation, or the decision to proceed. Depending on the circumstances, buyers may seek warranties, indemnities, escrow arrangements, or other contractual protections from the seller.
Planning the Transition After Purchase
Acquiring the company is only one stage of the process. A successful transition requires a plan for managing employees, maintaining customer relationships, protecting systems, and continuing product development.
Before closing, the buyer should identify which employees hold essential technical or operational knowledge. Retaining key personnel may help preserve institutional knowledge and reduce disruption.
Customers and business partners may also need clear communication about the change in ownership. The timing and method of these communications should be coordinated with contractual requirements and any applicable legal obligations.
An integration plan should define priorities for the first several months. These may include reviewing access permissions, confirming service continuity, assessing development projects, and establishing reporting procedures.
Buyers should avoid making unnecessary changes immediately after the acquisition without understanding how existing systems and relationships function. A measured transition can help protect the value of the business.
Questions to Ask Before Purchasing a Fintech Company
Before making an offer, prospective buyers should seek clear answers to several important questions.
- What are the company’s main sources of revenue?
- How has its financial performance changed over recent years?
- Which customers and commercial partners are most important?
- Who owns the software and related intellectual property?
- Are there unresolved security incidents or technical weaknesses?
- Which licences, registrations, or contractual approvals are required?
- What expenses will be necessary to maintain the product?
- Why is the current owner considering a sale?
- Which employees are essential to ongoing operations?
- What risks could affect revenue after the transaction?
The answers should be supported by appropriate documents and independent verification wherever possible.
Conclusion
A financial technology company for sale can provide an opportunity to enter a growing area of digital business, acquire established software, or expand an existing financial services operation. However, the attractiveness of an acquisition depends on the company’s real commercial position rather than its marketing claims.
Prospective buyers should evaluate financial records, technology ownership, customer relationships, cybersecurity, regulatory responsibilities, and future operating requirements before committing capital. Independent professional advice can help identify problems that may otherwise remain hidden until after the purchase.
With a defined acquisition strategy and a careful due diligence process, investors can compare opportunities more effectively and determine whether a fintech business supports their long-term objectives. The most suitable acquisition is one whose risks, financial requirements, and growth potential are clearly understood before ownership changes hands.