

Managing money can become challenging when you have several financial goals to balance. You may want to save for retirement, pay off debt, grow your investments, purchase property, or expand a business. Without a clear strategy, it can be difficult to decide which financial priorities deserve attention first.
Working with a financial consultant or financial advisor can help you understand your options and develop a practical plan for your financial future. Professional guidance can bring structure to your decisions, helping you make better use of your income while preparing for unexpected expenses and long-term responsibilities.
Understanding how financial planning services work is an important first step toward creating a financial strategy that reflects your needs, income, and personal goals.
What Does a Financial Consultant Do?
A financial consultant helps individuals, families, and business owners evaluate their current financial situation and identify opportunities for improvement. Depending on their qualifications and service offerings, consultants may provide guidance on budgeting, debt management, cash flow, investments, and long-term financial planning.
For example, someone with a steady income may still struggle to save because of high monthly expenses or multiple loan payments. A financial consultant can help review the available information, identify spending patterns, and develop a realistic plan for improving financial stability.
Common areas of financial consulting include:
- Budget management: Understanding where your money goes and identifying opportunities to save.
- Debt reduction: Creating a strategy for managing credit cards, personal loans, and other financial obligations.
- Cash flow planning: Balancing income, regular expenses, and future financial commitments.
- Investment planning: Evaluating investment options based on financial goals, risk tolerance, and time horizon.
- Business finances: Reviewing financing needs, operating costs, and future growth plans.
The right approach depends on your circumstances. Before hiring a consultant, ask about their qualifications, experience, service fees, and the specific services they provide.
How Is a Financial Advisor Different From a Financial Consultant?
The terms financial consultant and financial advisor are sometimes used interchangeably, but their responsibilities can differ depending on their professional credentials, services, and applicable regulations.
A financial consultant may focus on reviewing a financial situation and recommending ways to improve money management. A financial advisor may provide broader guidance on investments, retirement preparation, portfolio management, and other long-term financial goals.
However, job titles alone do not establish a professional’s qualifications or legal responsibilities. Some advisors specialize in investment management, while others focus on retirement income, wealth preservation, or comprehensive financial planning.
When comparing professionals, consider the following questions:
- What qualifications, licenses, or certifications do you hold?
- Which financial services do you provide?
- How are your fees calculated?
- Do you receive commissions or other compensation for recommending financial products?
- Are you required to act in my best interest when providing the services I need?
These questions help you evaluate whether a professional has the relevant expertise and whether their services align with your financial priorities.
What Are Financial Planning Services?
Financial planning services help you organize your finances around specific goals. Rather than treating savings, debt, investments, and retirement as separate concerns, a financial plan considers how these areas work together.
A comprehensive plan typically begins with an assessment of your income, expenses, assets, liabilities, and future objectives. Based on this information, a professional can help you establish priorities and develop an actionable strategy.
1. Budgeting and Expense Management
A budget helps you understand how much money comes in, how much goes out, and what remains available for saving or investing.
Start by reviewing your monthly income and separating essential expenses from discretionary spending. Housing, utilities, groceries, insurance, and debt payments should be considered alongside entertainment, subscriptions, and other optional costs.
A realistic budget should leave room for unexpected expenses rather than allocating every dollar to planned purchases. Reviewing your spending regularly can also reveal whether your current habits support your long-term goals.
2. Debt Management and Financial Stability
High-interest debt can make it harder to save and invest. A debt repayment strategy helps you determine how much you can afford to pay each month while maintaining enough money for essential expenses.
Two common approaches are the debt avalanche method, which prioritizes debts with the highest interest rates, and the debt snowball method, which focuses on paying off the smallest balances first.
The best choice depends on your interest costs, cash flow, and personal preferences. A financial professional can help you compare these approaches and evaluate whether refinancing or consolidating debt makes sense for your situation.
3. Retirement Planning
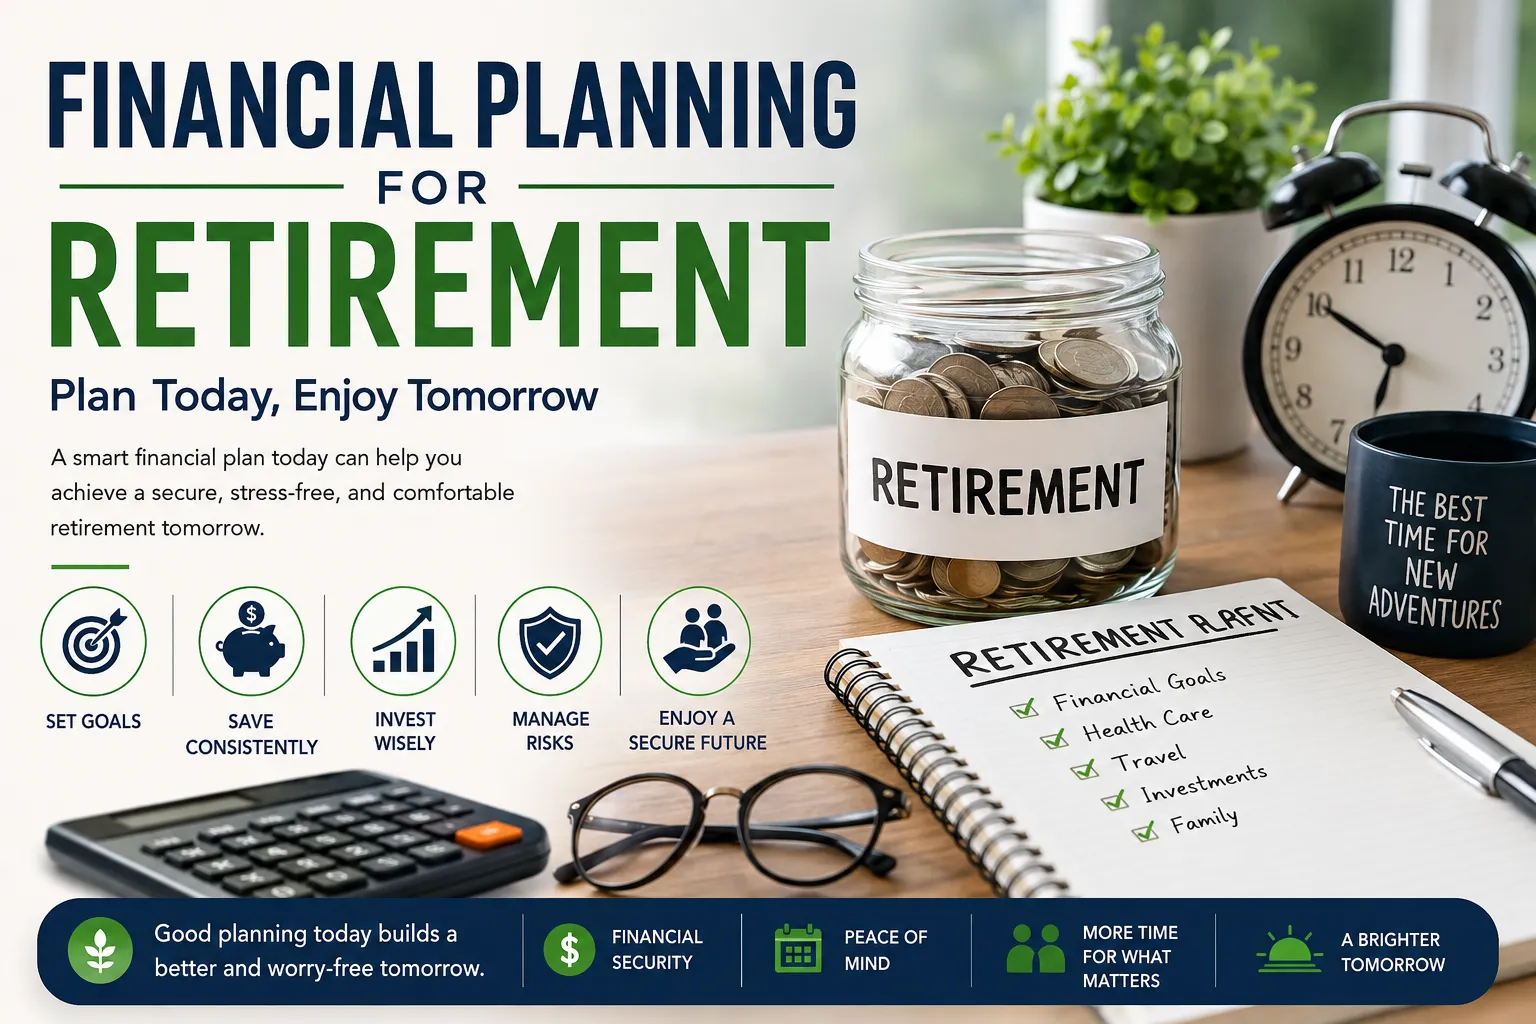
Retirement planning involves estimating future living expenses, reviewing potential income sources, and determining how much you may need to save.
Consider your expected retirement age, current savings, employer-sponsored retirement plans, pension benefits, and anticipated healthcare expenses. Inflation also matters because the cost of everyday necessities may rise over time.
Starting early can give your savings more time to grow, but people approaching retirement can benefit from reviewing their strategy as well. A retirement plan should address not only how much to save but also how to manage withdrawals and maintain a suitable balance between income needs and investment risk.
4. Investment and Wealth Management
Investment planning can help you decide how to allocate money across different asset classes according to your objectives and tolerance for risk.
Your investment strategy should reflect when you expect to need the money. Funds required in the near future generally call for different considerations than money intended for retirement decades away.
Diversification, investment costs, liquidity, and tax implications may all influence your decisions. No investment strategy guarantees a profit, so it is important to understand the risks before committing funds.
5. Financial Protection and Emergency Savings
Unexpected medical expenses, home repairs, job changes, and business disruptions can place pressure on your finances.
An emergency fund can help cover these expenses without relying entirely on credit cards or loans. The appropriate amount depends on your household costs, income stability, dependents, and other financial responsibilities.
Insurance coverage and estate planning may also be important parts of a broader financial strategy, depending on your circumstances.
Common Financial Planning Mistakes and How to Avoid Them
Even people with good incomes can experience financial difficulties when their decisions are not connected to a clear plan.
Ignoring small recurring expenses: Subscriptions, frequent purchases, and service fees can gradually reduce your ability to save. Review these expenses regularly and cancel services you no longer need.
Delaying retirement savings: Waiting until later in your career may require larger contributions to reach the same target. Start with an affordable amount and increase contributions when your income allows.
Making investment decisions based on emotions: Market fluctuations can encourage impulsive buying or selling. Establish a strategy based on your goals, time horizon, and risk tolerance instead of reacting to every market movement.
Failing to prepare for emergencies: Without accessible savings, unexpected costs may lead to expensive borrowing. Build an emergency reserve gradually and keep it separate from money intended for long-term investments.
Setting unclear financial goals: A general desire to become financially secure is difficult to measure. Set specific targets, such as saving a particular amount for retirement or reducing a loan balance by a certain date.
These improvements may seem small, but consistent financial habits can make it easier to manage uncertainty and work toward meaningful goals.
How to Choose the Right Financial Professional
Selecting a financial professional requires more than comparing service prices. You should understand how the person works, what expertise they offer, and whether their recommendations suit your needs.
Begin by identifying your main objective. You may need help with retirement planning, household budgeting, investment decisions, business cash flow, or a combination of these areas.
Next, review the professional’s credentials and relevant experience. Ask for a clear explanation of their fees, including any commissions, account charges, or additional service costs. You should also understand whether the professional provides one-time consultations or ongoing financial support.
Finally, choose someone who communicates clearly and explains both the potential benefits and the risks of different strategies. You should feel comfortable asking questions and discussing your financial priorities without pressure to purchase products you do not need.
How to Build a Financial Plan That Works for You
You do not need to solve every financial challenge at once. A step-by-step approach can make the process easier to manage.
- Review your current position. Calculate your income, expenses, savings, investments, and outstanding debts.
- Set clear financial goals. Identify short-term needs, medium-term plans, and long-term objectives.
- Prioritize urgent concerns. Address essential bills, expensive debt, and immediate financial risks.
- Create a savings strategy. Decide how much you can regularly set aside for emergencies and future goals.
- Review your investment and retirement plans. Check whether your current approach matches your time horizon and risk tolerance.
- Monitor your progress. Review your budget and financial goals regularly, particularly after major life or income changes.
Professional financial planning services can provide additional structure, especially when you have multiple goals or complex financial responsibilities. Your plan should remain flexible enough to adapt when your circumstances change.
Conclusion
Better financial decisions begin with understanding your current situation and establishing realistic goals. A financial consultant can help you identify ways to improve cash flow and manage debt, while a financial advisor may provide guidance on investments, retirement preparation, and long-term financial priorities, depending on their expertise.
With a clear strategy, regular reviews, and informed professional support, you can make more confident decisions about saving, spending, investing, and preparing for the future. The most effective financial plan is one that fits your circumstances and evolves as your needs change.