

A low credit score can make everyday financial goals more difficult. You might struggle to qualify for a loan, receive less favorable interest rates, or face additional questions during a rental application. When you review your credit report, you may discover late payments, collection accounts, high balances, or information you do not recognize.
The challenge is knowing what to do next. Should you dispute the entry, contact the creditor, pay the debt, or seek professional assistance?
The answer depends on the problem. Credit clean up starts with understanding whether the information is inaccurate, the debt is legitimate, or your current financial habits need attention. Taking the right approach can help you avoid unnecessary expenses and focus on realistic ways to improve your credit profile.
For people seeking credit repair in Philadelphia, the following steps provide a practical starting point.
1. Determine Why Your Credit Score Is Low
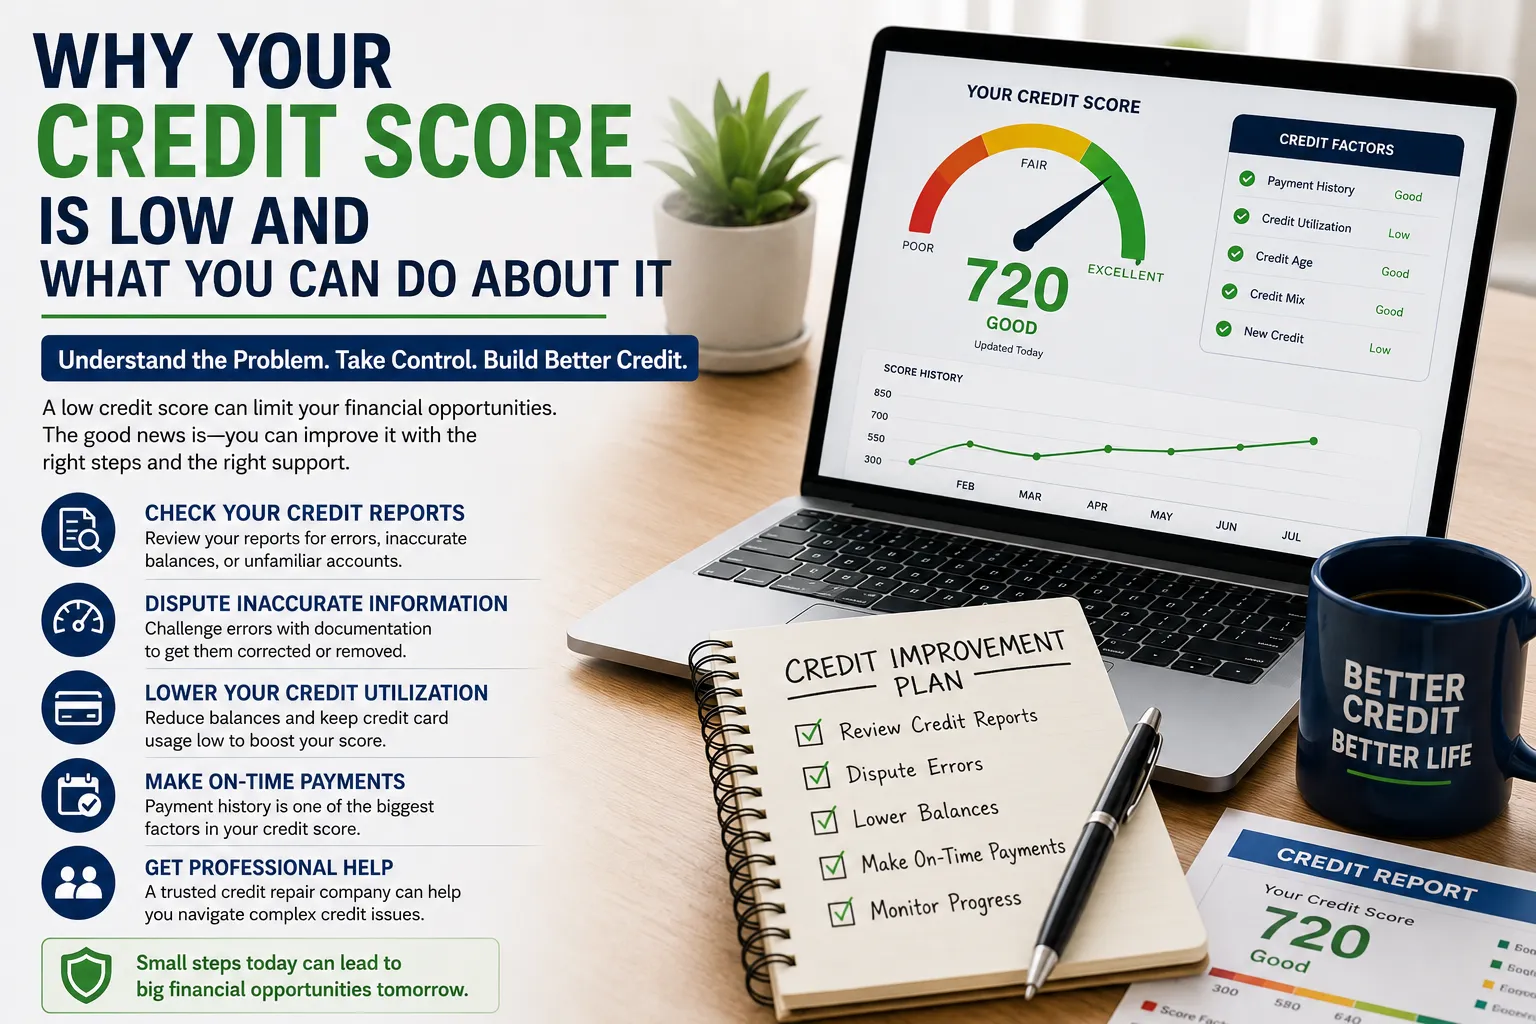
Before trying to remove credit report entries, review the information that may be affecting your score. Obtain reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com.
Your reports may contain different information, so reviewing all three can help you identify problems that would otherwise go unnoticed.
Look for these common issues:
-
Late payments: Payments reported as overdue when you believe they were made on time.
-
Collection accounts: Debts transferred or assigned to collection agencies.
-
High credit utilization: Credit card balances that use a large portion of available limits.
-
Duplicate reporting: Entries that appear more than once and incorrectly represent the same obligation.
-
Incorrect balances: Amounts that do not match your account statements or payment records.
-
Unfamiliar accounts: Accounts that may indicate a reporting error, a mixed credit file, or identity theft.
-
Outdated information: Negative entries that may have exceeded the applicable credit reporting period.
Create a checklist of every questionable entry. Record the account name, reporting bureau, balance, account status, and the reason you believe something may be wrong.
This simple process gives you a clearer picture of your credit history and helps you decide which issues need immediate attention.
2. Learn When You Can Remove Credit Report Information
Not every negative entry qualifies for removal. The distinction between inaccurate information and accurate negative information is essential.
If a credit report contains a payment that was incorrectly marked late, an account that does not belong to you, or a balance that is wrong, you can generally dispute the information with the credit bureau and, where appropriate, the company that supplied it.
However, accurate negative information generally cannot be removed simply because it lowers your score. Many negative items can remain on credit reports for around seven years, depending on the type of information and applicable rules. Certain bankruptcy information may remain longer.
For example, suppose a collection account appears on your report even though you paid the debt and have a letter confirming the settlement. If the account’s reported status is inaccurate, you can submit the letter as evidence and request an investigation.
On the other hand, if a late payment was correctly reported, disputing it without a legitimate reason is unlikely to resolve the problem.
The goal is to correct inaccurate information, not to erase a legitimate credit history.
3. Submit a Clear Dispute With Supporting Evidence
Once you identify a genuine error, prepare a focused dispute rather than sending a vague complaint.
A useful dispute should explain:
-
Which account or entry contains the error.
-
What information you believe is inaccurate or incomplete.
-
Why the reported information does not match your records.
-
Which documents support your explanation.
-
What correction you are requesting.
Supporting documents may include bank statements, payment confirmations, account statements, settlement letters, or correspondence from the creditor.
Keep copies of all submissions and responses. Credit bureaus generally have 30 days to investigate qualifying disputes, although certain circumstances can extend the period to 45 days.
If the information is corrected, review the updated report to confirm the result. If the dispute is unsuccessful and you still believe the information is inaccurate, examine the explanation, gather additional evidence if available, and consider the appropriate next step.
4. Handle Legitimate Collection Accounts Carefully
A collection account does not always mean you should immediately pay whatever amount appears on your report. First, verify the account and understand your options.
If a collector contacts you about a debt you do not recognize, request appropriate information to help determine whether the debt is yours. Compare the amount, original creditor, and account details with your own records.
If the debt is legitimate, consider your budget and available options before making an arrangement. You may be able to discuss a payment plan or settlement with the creditor or collection agency, but obtain the terms in writing before sending payment.
Be particularly cautious with older debts. The time a debt may remain on a credit report is different from the statute of limitations for a lawsuit to collect it. Depending on applicable law and your circumstances, acknowledging or paying an old debt can have legal consequences.
If you are unsure about an older debt, consider consulting a qualified consumer-law attorney before taking action.
Remember that paying or settling a collection account does not automatically guarantee that it will be removed from your credit report. The reported status should accurately reflect the outcome.
5. Fix Bad Credit by Improving Your Current Financial Habits
Even when every negative entry is accurate, you can still work toward a stronger credit profile.
Reduce high credit card balances
Credit utilization measures how much of your available revolving credit you are using. For example, a $1,200 balance on a card with a $2,000 limit represents 60% utilization.
If possible, gradually reduce high balances while keeping up with required payments. Lower utilization may benefit many credit scoring models, although the exact effect varies by individual credit profile.
Protect your payment history
Set payment reminders or use automatic payments where appropriate. Check that payments are processed successfully and that sufficient money is available in your account.
If you cannot afford your current payments, contact creditors to ask whether hardship arrangements or other assistance options are available.
Avoid unnecessary credit applications
Applying for multiple credit products in a short period can result in additional hard inquiries. Before submitting an application, review the eligibility criteria and consider whether the account fits your financial situation.
Monitor your credit reports
Review your reports periodically to check for errors, unfamiliar accounts, and changes in account status. If you suspect identity theft, consider appropriate fraud alerts or credit freezes.
These habits may not produce instant results, but they can help establish a more sustainable foundation for credit improvement.
6. When Should You Work With a Credit Repair Specialist?
Handling several credit report errors, collections, and disputes can become complicated. A credit repair specialist may help you organize your reports, identify potentially inaccurate entries, prepare dispute documentation, track responses, and understand possible next steps.
When comparing credit repair Philadelphia services, ask each provider:
-
What specific services are included?
-
How will you determine whether an entry may be inaccurate?
-
What fees apply, and when are payments due?
-
Will I receive copies of disputes and correspondence?
-
What are the cancellation terms?
-
Can I complete these steps independently for free?
Credit repair organizations are subject to federal requirements, including restrictions on advance payments and requirements for certain disclosures. Be cautious of anyone who guarantees a particular score, promises to remove all negative information, or recommends creating a false identity.
You can dispute inaccurate information yourself without paying a credit repair company. Professional assistance should offer clear value, transparent fees, and realistic expectations.
Final Thoughts
Credit problems can feel overwhelming when you are unsure whether to dispute an entry, pay a debt, or seek professional assistance. The best approach is to identify the cause before committing time or money to a solution.
Review your reports, dispute genuine inaccuracies, verify collection accounts, and build consistent financial habits. If your situation involves multiple complicated issues, a credit repair specialist may help you understand the available options.
For Philadelphia residents looking to fix bad credit, effective credit clean up is about more than removing negative entries. It means correcting reporting errors, managing legitimate obligations, and making informed financial decisions that support your long-term goals.