

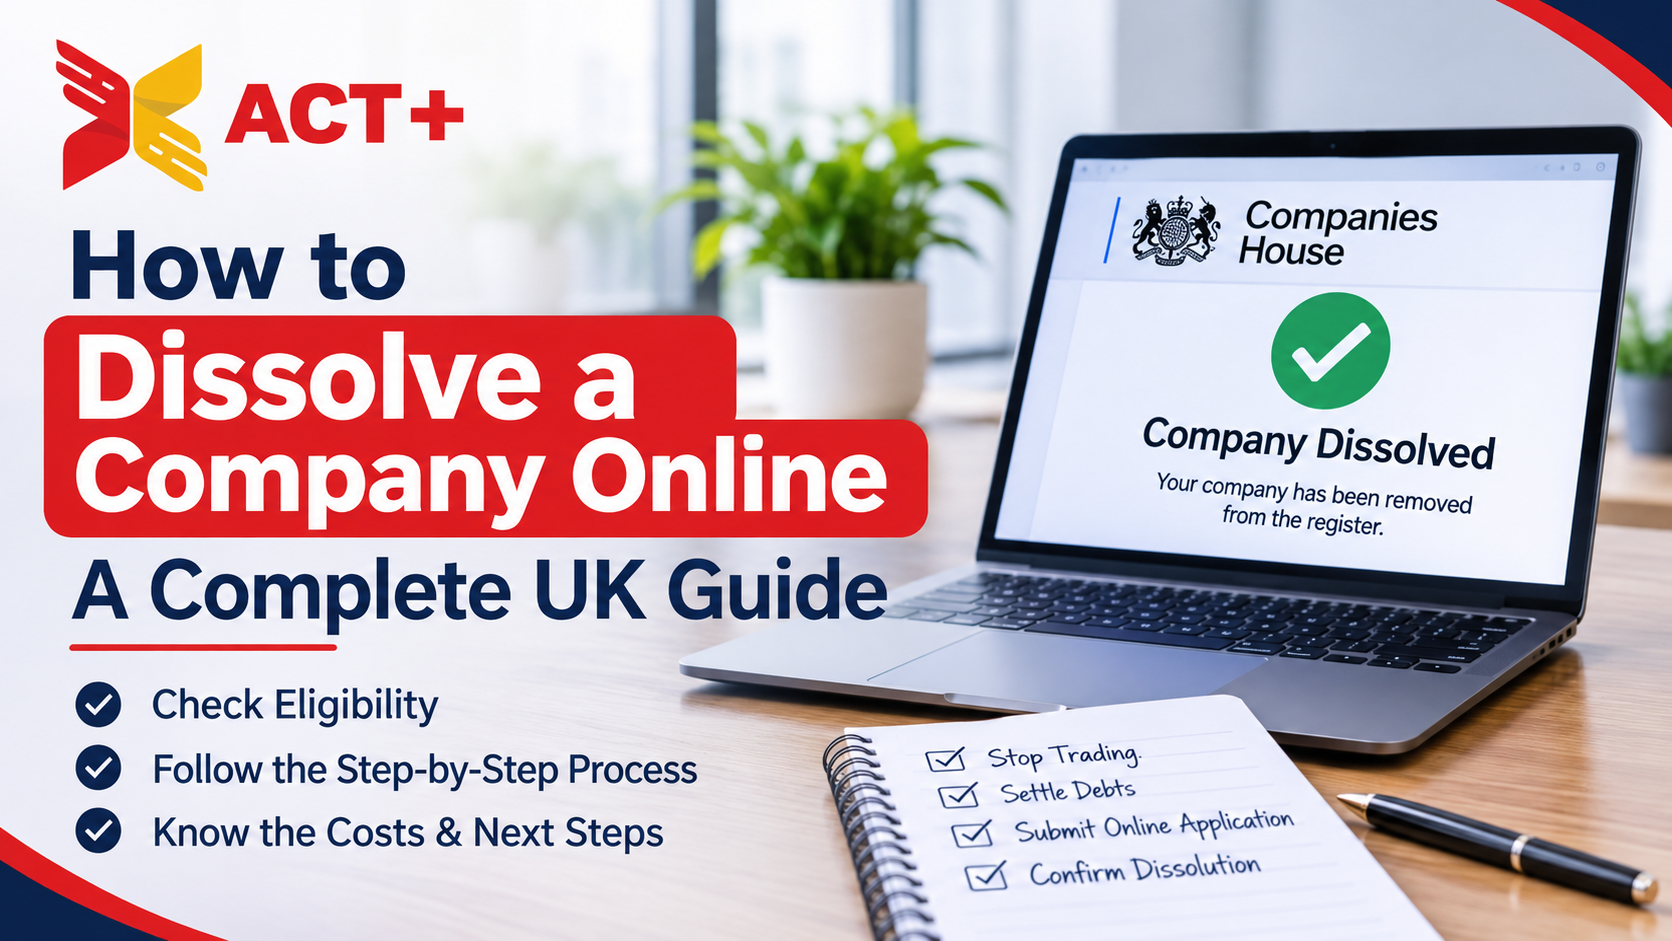
Closing a business is not always an easy decision. Whether you are retiring, moving on to a new opportunity or simply no longer need your limited company, it is important to close it correctly. Fortunately, eligible UK company directors can now dissolve a company online through Companies House without dealing with lengthy paper-based procedures.
However, closing a company involves more than submitting an application. Directors must consider outstanding debts, tax responsibilities, company assets and legal obligations before starting the process. Failing to complete these steps properly can lead to delays, objections or future complications.
This guide explains how to dissolve a company, who can apply, what documents are required and what happens after Companies House receives the application.
What Does It Mean to Dissolve a Company?
Dissolving a company means officially removing it from the Companies House register. Once the process is complete, the company legally ceases to exist and can no longer operate as an active business.
For many small business owners, voluntary strike-off is a straightforward way to close a company that is no longer required. It is generally suitable for businesses that have stopped trading, have no outstanding business activities and meet the relevant legal requirements.
Company dissolution should not be confused with liquidation. Liquidation is a formal insolvency procedure that involves dealing with company assets and liabilities, particularly where a business cannot pay its debts.
If a company is solvent and meets the eligibility conditions, voluntary strike-off may provide a simpler alternative.
Who Can Apply to Dissolve a Company Online?
Not every company qualifies for voluntary dissolution. Before submitting an application, directors should check whether their business meets the Companies House requirements.
Generally, a company may apply for voluntary strike-off if:
- It has stopped trading and is no longer carrying on business.
- It has not traded or carried on business during the previous three months.
- It has not changed its company name during the previous three months.
- It has not sold company property or rights as part of its normal trading activities during the previous three months.
- It is not involved in ongoing insolvency proceedings.
- It is not subject to a relevant arrangement with creditors or members.
The company must also deal with its outstanding responsibilities before applying.
It is important to understand that voluntary strike-off is not a way to avoid paying creditors or escaping financial obligations. Directors who submit an application when their company is not eligible may face legal consequences.
How to Dissolve a Company Online: Step-by-Step Process
If your company meets the eligibility requirements, you can begin the online dissolution process. Following the correct steps can help prevent unnecessary delays.
1. Stop Trading and Complete Business Activities
The first step is to stop carrying out normal business activities.
Before applying, directors should make sure that the company has completed its remaining transactions. This may include:
- Stopping sales and accepting new orders.
- Cancelling business contracts and subscriptions.
- Collecting outstanding customer payments.
- Paying suppliers and other creditors.
- Closing unnecessary business accounts.
- Dealing with outstanding customer refunds.
You should also ensure that the company is not involved in any activity that would make it ineligible for voluntary strike-off.
2. Settle Outstanding Debts and Financial Obligations
Before you dissolve a company online, review its financial position carefully.
Outstanding debts should be addressed, including payments owed to suppliers, lenders, employees and other creditors. Directors should also review any outstanding tax liabilities.
If the company cannot pay its debts when they become due, voluntary strike-off may not be appropriate. In such circumstances, professional insolvency advice may be necessary.
Ignoring creditors or submitting a dissolution application to avoid financial responsibilities can create serious problems for directors.
3. Complete Your Tax Responsibilities
Tax compliance is another important part of closing a limited company.
Depending on the company’s circumstances, you may need to:
- Submit outstanding Corporation Tax returns.
- Pay any Corporation Tax owed to HMRC.
- Submit final VAT returns and cancel VAT registration.
- Deal with outstanding PAYE responsibilities.
- Complete final payroll submissions if the company employs staff.
- Inform HMRC that the company has stopped trading.
If the company is registered for VAT, its registration should be cancelled when it stops making taxable supplies, subject to the applicable rules.
It is also important to resolve any outstanding HMRC refunds before dissolution. Once the company is dissolved, HMRC cannot issue refunds to it in the normal way.
4. Deal With Company Assets
One of the most commonly overlooked aspects of company dissolution is the treatment of business assets.
Before submitting an application, directors should identify and properly deal with any remaining assets, including:
- Money held in company bank accounts.
- Vehicles and equipment.
- Business property.
- Intellectual property.
- Outstanding customer payments.
- Website domains and digital assets.
Any remaining assets at the date of dissolution generally pass to the Crown under the legal principle known as Bona Vacantia.
This means that directors should not assume they can recover company money or property after dissolution without taking the appropriate legal steps.
5. Notify Interested Parties
Directors have a legal responsibility to inform relevant people about the company’s proposed dissolution.
Within seven days of submitting the application, a copy must be sent to the relevant parties, which may include:
- Company shareholders.
- Creditors.
- Employees.
- Pension scheme managers or trustees.
- Directors who did not sign the application.
This requirement is important because interested parties must have an opportunity to raise concerns or object to the proposed strike-off.
Keeping evidence that the relevant parties have been notified is a sensible precaution.
6. Submit the Online Application to Companies House
Once the necessary preparations are complete, you can submit your application through the official Companies House online service.
The application requires the company’s details and confirmation that the relevant conditions have been met.
A majority of the company’s directors must support the application.
The online application fee is currently £13. Directors can pay using a debit or credit card.
You can access the official service here:
Apply to close your company online – Companies House
The online process includes checks to help applicants complete the application correctly.
7. Wait for the Gazette Notice
After receiving the application, Companies House reviews the information.
If the application is accepted, a notice of the proposed strike-off is published in the relevant Gazette.
This gives interested parties an opportunity to object if they have valid reasons.
If no objection or other reason for delaying the process arises, the company will generally be struck off no earlier than two months after the first Gazette notice.
A second Gazette notice confirms the company’s dissolution.
At this stage, the company legally ceases to exist.
How Much Does It Cost to Dissolve a Company Online?
The cost of dissolving a company depends on how the application is submitted.
Companies House currently charges:
- Online application: £13.
- Paper application: £18.
The online option is generally quicker and less expensive.
However, these are only the official application charges. Businesses may also need to pay for accountancy services, outstanding tax liabilities, professional advice or other costs associated with closing the company.
For this reason, directors should review the company’s financial position before beginning the process.
What Happens After a Company Is Dissolved?
Once Companies House completes the strike-off, the company is removed from the register and loses its legal existence.
This has several important consequences.
Company bank accounts are frozen: Any remaining balance generally passes to the Crown.
Business assets pass to the Crown: Property, money and other assets still owned by the company may become Bona Vacantia.
The company cannot continue trading: It no longer exists as a legal entity and cannot carry out normal business activities.
Outstanding matters may remain relevant: Dissolution does not necessarily remove every potential claim or responsibility connected with the company’s previous activities.
Directors should therefore make sure that all important matters have been dealt with before the dissolution is completed.
Can a Dissolved Company Be Restored?
Yes. Under certain circumstances, a dissolved company can be restored to the Companies House register.
This may become necessary if directors discover that the company still owns assets, has outstanding funds in a bank account or needs to continue its business activities.
There are two main restoration routes:
Administrative restoration: This route may be available to eligible former directors or shareholders where Companies House struck the company off and the statutory conditions are satisfied.
Court restoration: This route may be required where administrative restoration is unavailable, including certain cases involving voluntary strike-off or applications by creditors and other interested parties.
The correct route depends on how the company was dissolved, who is applying and the company’s circumstances.
If you want to understand the process in more detail, read this guide to when a dissolved company can be restored.
It explains the main restoration requirements, eligibility conditions and available options.
Common Mistakes to Avoid When Dissolving a Company
Although it is possible to dissolve a company online, mistakes during the process can create unnecessary complications.
Here are some common issues directors should avoid.
Ignoring outstanding debts: Directors should not use voluntary strike-off as a method of avoiding creditors.
Forgetting HMRC obligations: Unsubmitted tax returns, unpaid Corporation Tax and VAT responsibilities should be addressed before dissolution.
Leaving money in the bank account: Remaining balances may pass to the Crown when the company is dissolved.
Failing to notify interested parties: Not sending the application to relevant individuals and organisations within the required period can lead to legal consequences.
Applying too early: Directors should check the three-month eligibility restrictions and ensure that all necessary business activities have been completed.
Assuming dissolution is always permanent: In certain circumstances, a dissolved company can be restored through the appropriate legal process.
Taking professional advice before submitting an application can help directors avoid these problems.
Final Thoughts
Choosing to close a limited company is an important business decision. Understanding how to dissolve a company correctly can make the process more straightforward and help directors avoid unnecessary legal and financial complications.
Eligible businesses can dissolve a company online through Companies House by completing their financial and tax responsibilities, dealing with company assets, notifying interested parties and submitting the required application.
However, directors should remember that dissolution has permanent legal consequences unless the company is subsequently restored. Taking time to prepare properly can protect business interests and make the closure process much smoother.