

Every sale a business makes ends with a moment of trust, when a customer hands over a card, taps a phone, or types details into a checkout page. Behind that simple action sits a chain of banks, networks, and software that must work together within seconds. Understanding payment processing merchant services helps owners see where their money travels, what they pay for, and which choices affect speed, security, and profit. Many small businesses sign up for the first offer they receive and later discover high fees, long contracts, or limited support. A little knowledge up front prevents these problems. This guide explains how card transactions move, which costs to compare and how to protect customers, so that business owners can choose a setup that suits their size, sales channels and growth plans.
How a Card Transaction Moves From Tap to Deposit
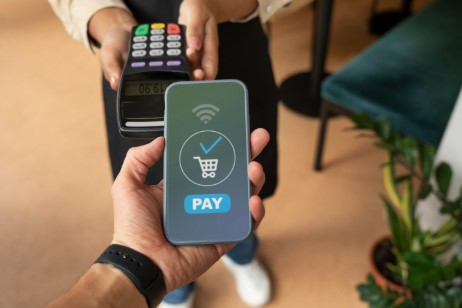
When a customer pays by card, the terminal or website sends the details to a payment processor, which forwards them to the card network and then to the customer’s issuing bank. The issuer checks the balance and fraud signals and replies with an approval or decline, usually within two or three seconds. This step is called authorization. Later, in a step called settlement, the funds move from the issuer to the merchant’s account, typically within one to three business days. Several parties take part in this flow: the merchant, the acquiring bank, the processor, the card network, and the issuer. When business owners study payment processing merchant services, they should know that a merchant account is the arrangement that lets a business accept card payments, while a payment gateway securely passes online transaction data. Some providers bundle these pieces together, whereas others separate them, and the structure affects pricing and flexibility. In-person sales rely on terminals or mobile readers, and online sales use hosted checkout pages or integrated plugins. Businesses that sell across several channels should confirm that one provider can report on all of them in a single dashboard, which saves time during bookkeeping and reconciliation.
Fees, Contracts and Features Worth Comparing
Costs are the most common source of confusion. Interchange fees are set by card networks and paid to issuing banks, assessment fees go to the networks, and the processor adds its own markup. Pricing models include flat rate, interchange plus, and tiered, and each suits different volumes. Flat rate is simple and works well for low volumes, interchange plus is more transparent for growing businesses, and tiered pricing can hide costs behind vague categories. Beyond the per-transaction rate, ask about monthly fees, statement fees, chargeback fees, early termination penalties, and equipment leases. Reading the contract carefully matters, because auto-renewal clauses can lock a business in for years. Features deserve equal attention. Look for recurring billing, invoicing, mobile acceptance, inventory integration and fast customer support. When assessing payment processing merchant services, also check how disputes are handled, since chargebacks can erode margins quickly. Request a sample statement and a written fee schedule so you can compare providers on equal terms. Ask also about payout speed, because faster access to funds improves cash flow for businesses with tight margins.
Conclusion
Protecting customer data is both a legal duty and a trust builder. Businesses that accept cards must follow the Payment Card Industry Data Security Standard, which sets rules for storing and transmitting card information. Useful safeguards include encryption, tokenization, which replaces card numbers with unusable substitutes, and EMV chip support to reduce counterfeit fraud. Two-factor authentication on account dashboards and regular staff training add further protection. Fraud tools such as address verification and velocity limits help flag suspicious activity before it becomes a loss. Some owners look at established local providers such as Best Products Sales & Service, inc. when comparing how different companies describe their support and equipment options, though every offer should be verified independently. Whatever route you take, treat payment processing merchant services as a long-term partnership rather than a one-time purchase. Review your statements every month, revisit your pricing as volumes grow, and keep documentation of every agreement. A careful choice today protects margins, reduces disputes, and keeps customers confident at every checkout.